

Bank Fraud Hitting Seniors the Hardest
Majority of the $2 billion-plus in losses are from U.S. citizens over the age of 60
- |
- Written by Banking Exchange staff
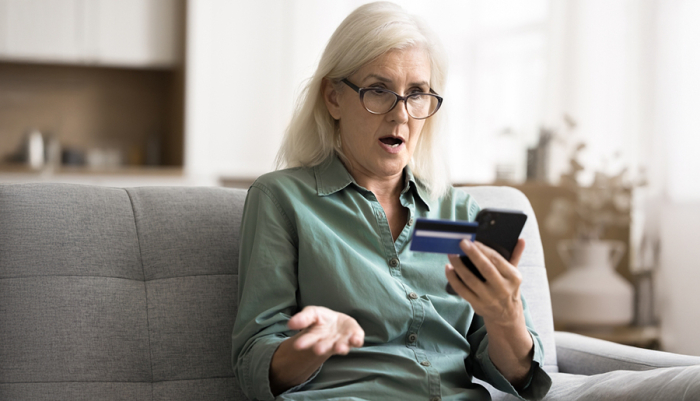
A report published this week by the FTC (Federal Trade Commission) showed that seniors are taking a disproportionate hit when it comes to financial fraud.
The majority of the $2 billion-plus in losses reported are from United States citizens over the age of 60.
However, the FTC said the number, including investment scams, is probably more than $80 billion.
The stress that this brings, especially over the holidays, on seniors is substantial, as seniors already are anxious about financial security.
Financial fraud is increasing overall year over year, and particularly with schemes that steal more than $100,000 from individuals.
Banks, however, have taken notice of the trend, and fraud prevention is one of the top priorities stated in multiple surveys of bankers for 2026.
Tagged under Risk Management; Lending; Consumer Credit; The Economy; Cyberfraud/ID Theft; Feature; Feature3; Fraud;
Related items
- Tokenized Deposit Networks: A Practical Guide for the Banking C-Suite in 2026
- U.S. Bank Completes First Live USBDC Stablecoin Transaction
- Robinhood Targets Bigger Role in IPO Underwriting
- JPMorgan Cuts Lending to AI-Focused Hedge Fund After Losses
- Social Engineering Is Changing the Fraud Prevention Game for Banks and Credit Unions